First Option Mortgage reaches 65% conversion by making automated verifications the default in Encompass
About
First Option Mortgage is an independent mortgage lender headquartered in Suwanee, Georgia, just outside Atlanta. Founded in 2004, the company has grown to more than 300 employees, with nine branch locations and licenses in more than 35 states and Washington, D.C. Guided by the belief that mortgages are about people, not just numbers and rates, First Option is big enough to invest in the staff and systems that move the industry forward, yet small enough to stay nimble. That mindset shows up in its operations team, which treats constant improvement as part of the job and builds custom workflows to give borrowers a simpler, clearer path to closing.
Challenge
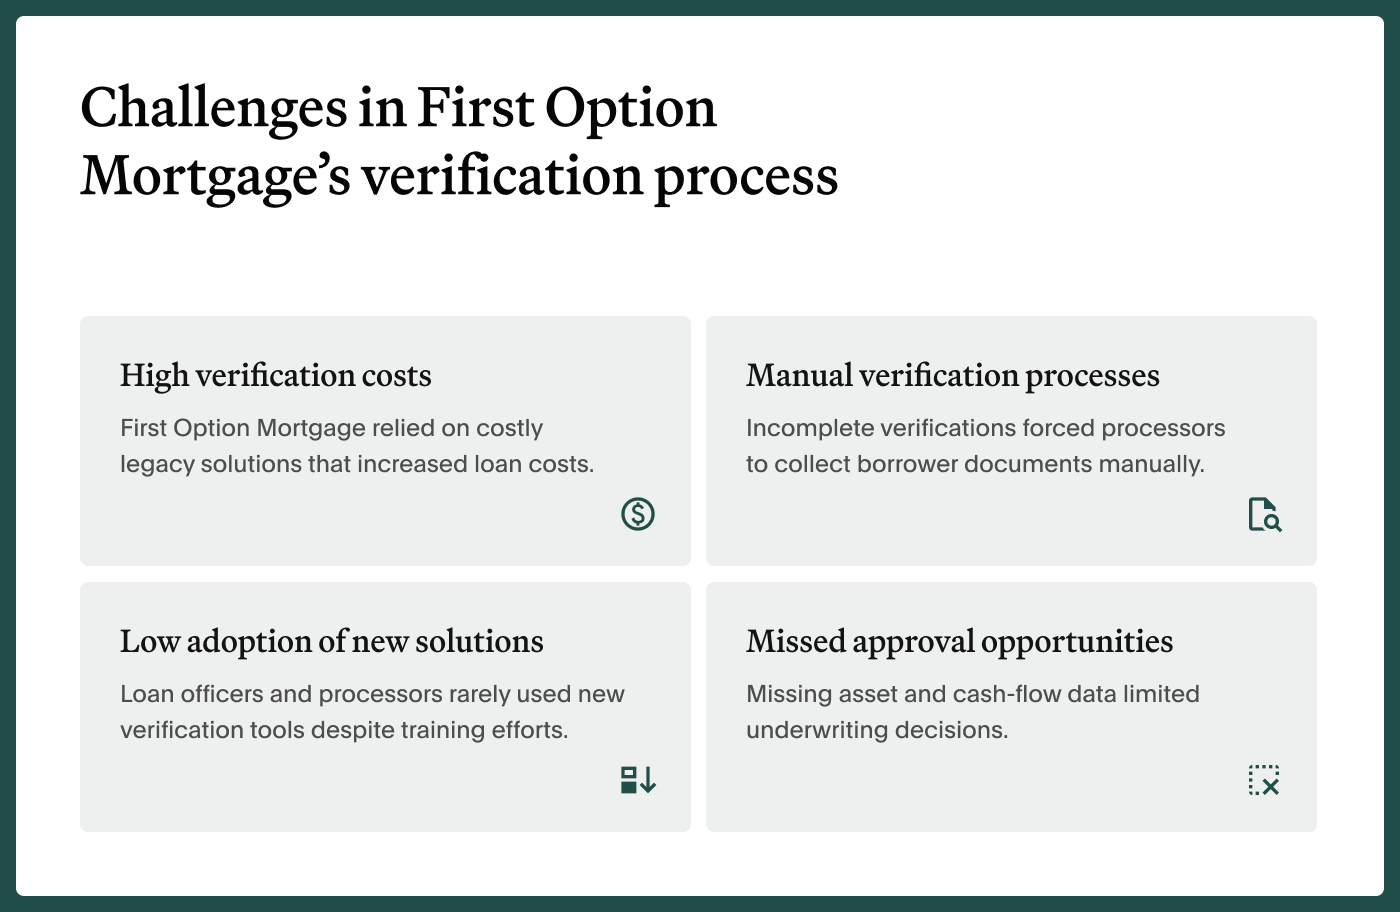
For years, First Option Mortgage had to pay premium prices to verify a borrower’s income, employment, and assets, starting with a legacy database solution. Those orders drove up the cost of each loan. If a verification came back incomplete, processors fell back on the manual routine of collecting pay stubs, W‑2s, bank statements, and tax returns by phone or email.
Over time, First Option tried different verification options designed to reduce costs and manual effort, but getting loan officers and processors to use them consistently proved difficult. The operations team would train employees and make a new service available, only to find that very few people actually used it.
"We'd train 100 people on the latest verification solution, but then when we looked at the numbers, only 12 people ever clicked the button," says Kevin Strika, vice president of operations at First Option.
When an asset verification required a loan officer or processor to remember to order it separately, it often was not ordered at all. That meant bank-account data that could strengthen the automated underwriting decision never made it into the file. In some cases, borrowers who did not initially receive an approval might have gotten a different result if the system had been able to consider their cash flow or positive rental payment history.
"From a management perspective, it was incredibly frustrating to invest in new verification options and see so few people actually use them," Strika says.
First Option needed a verification strategy that lowered costs, sent borrowers only the requests relevant to their loans, and ran automatically instead of relying on loan officers or processors to initiate it.
Solution
First Option first looked to Argyle as a lower-cost alternative to legacy database employment verifications. Over time, Argyle expanded what First Option could verify through the platform, adding broader income verification capabilities and direct-source asset verification alongside its payroll-connected income and employment solution. At the same time, Fannie Mae and Freddie Mac broadened their acceptance of data verified through these methods. Together, those developments gave First Option an opportunity to move beyond reducing employment verification costs and use Argyle as the foundation for a more standardized process across income, employment, and asset verifications.
"The ability to use Argyle across income, employment, and asset verification really put our strategy into high gear. We started looking at Argyle less as a cost reduction measure and more as a process improvement measure," Strika says.
In August 2025, First Option went live with Argyle through its integration with ICE Mortgage Technology's Encompass® loan origination system, using Encompass Automated Service Ordering (ASO) to automate verification requests.
Rather than making Argyle another option for loan officers and processors to remember, the team made it the default. Requests now go out automatically with initial disclosures, when borrowers are already engaged in the process, removing the manual step that had limited adoption in the past. Loan officers receive an automatic email when a request is sent and another notification once the borrower connects. The timing also avoids ordering so early that verifications could expire before a borrower finds a home or so late that manual documents are already in the file
"We don't need a loan officer to click a button or a processor to remember to order the verification,” Strika says. “It goes out automatically."
First Option also built custom Encompass logic that reads the 1003 at the borrower level. For example, a borrower qualifying on Social Security income never receives a payroll request. If there is no cash to close, no bank request goes out. When two borrowers are on a loan but only one income is being used, only that borrower gets the request.
First Option waited to roll out Argyle’s bank-derived asset verification until it could be automated in the same way. Once Argyle added ASO support for bank connections in May 2026, First Option turned it on right away, bringing income, employment, and assets into a single automated workflow.
"What we've accomplished together with Argyle is one of the most meaningful tech transformations I’ve seen in my time in the industry," Strika says.
Results
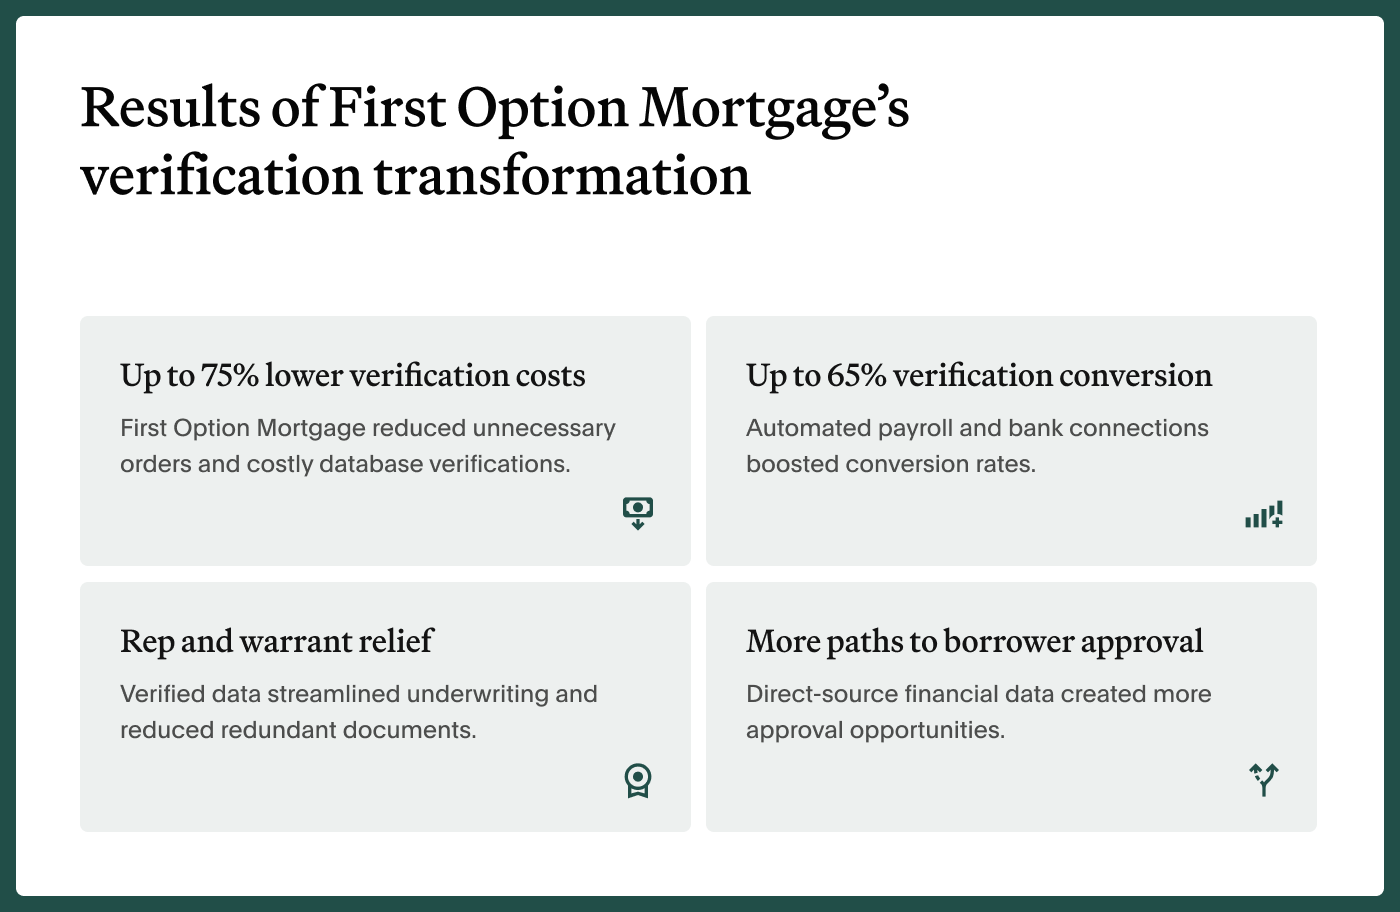
Up to 75% lower verification costs compared to The Work Number
Because First Options now sends only the verification requests each borrower actually needs, it has reduced both unnecessary orders and its reliance on premium database verifications.
"We're not wasting money,” Strika says. “We're sending the right request to the right borrower at the right time."
Up to 65% conversion since adding bank connections
Going in, the team heard every reason borrowers might not complete a payroll connection. Once the process was automated, borrowers proved those assumptions wrong. First Option has maintained a conversion rate above 54% across hundreds of payroll-based income and employment verifications year to date. And since Argyle’s bank connections joined the automated ASO workflow in May 2026, First Option has seen conversion climb even further to roughly 65% across employment, income, and asset verifications..
Rep and warrant relief and cleaner loan files
Income and asset data verified through Argyle may qualify for representation and warranty relief through applicable Fannie Mae and Freddie Mac programs. First Option customized Encompass’s Rep and Warrant Tracker so underwriters can see when a loan component is eligible for relief from their first review, helping them avoid unnecessary conditions and remove redundant documents before delivery.
More paths to borrower approval
Direct-source bank data gives the GSEs additional information they can use to assess a borrower’s financial profile, including positive rental payment history and cash flow. For borrowers who might not receive an approval based on the initial file alone, that additional data can provide another path to an approve recommendation. For First Option’s loan officers, that means more opportunities to find a way forward for borrowers whose files might otherwise stall.
Want to learn more about First Option’s journey? Watch our webinar: The Path to Faster, Smarter Verifications.