$10,936 to Originate, $973 to Keep: Where Verification Fits in Current Loan Economics
In the second quarter of 2026, independent mortgage banks and bank mortgage subsidiaries spent an average of $10,936 to originate a single loan and earned a pre-tax production profit of $973 on it. That was a better quarter than the first — costs fell $962 per loan, and profit rose from $727. But the relief is thin. At 25 basis points, production margins are still below MBA's long-run average of 39 basis points, and cost per loan is still running nearly 40% above the $7,903 long-run average production expense since 2008. And Q2 closed before rates turned higher in September. One good quarter doesn't change the underlying math: the margin absorbing those costs is still thin enough to be erased by a handful of line items moving the wrong direction.
That's the context every vendor conversation in 2026 happens inside. And it's why a per-pull verification fee — easy to wave through as a pass-through cost when margins were fat in 2021 — deserves a harder look now.
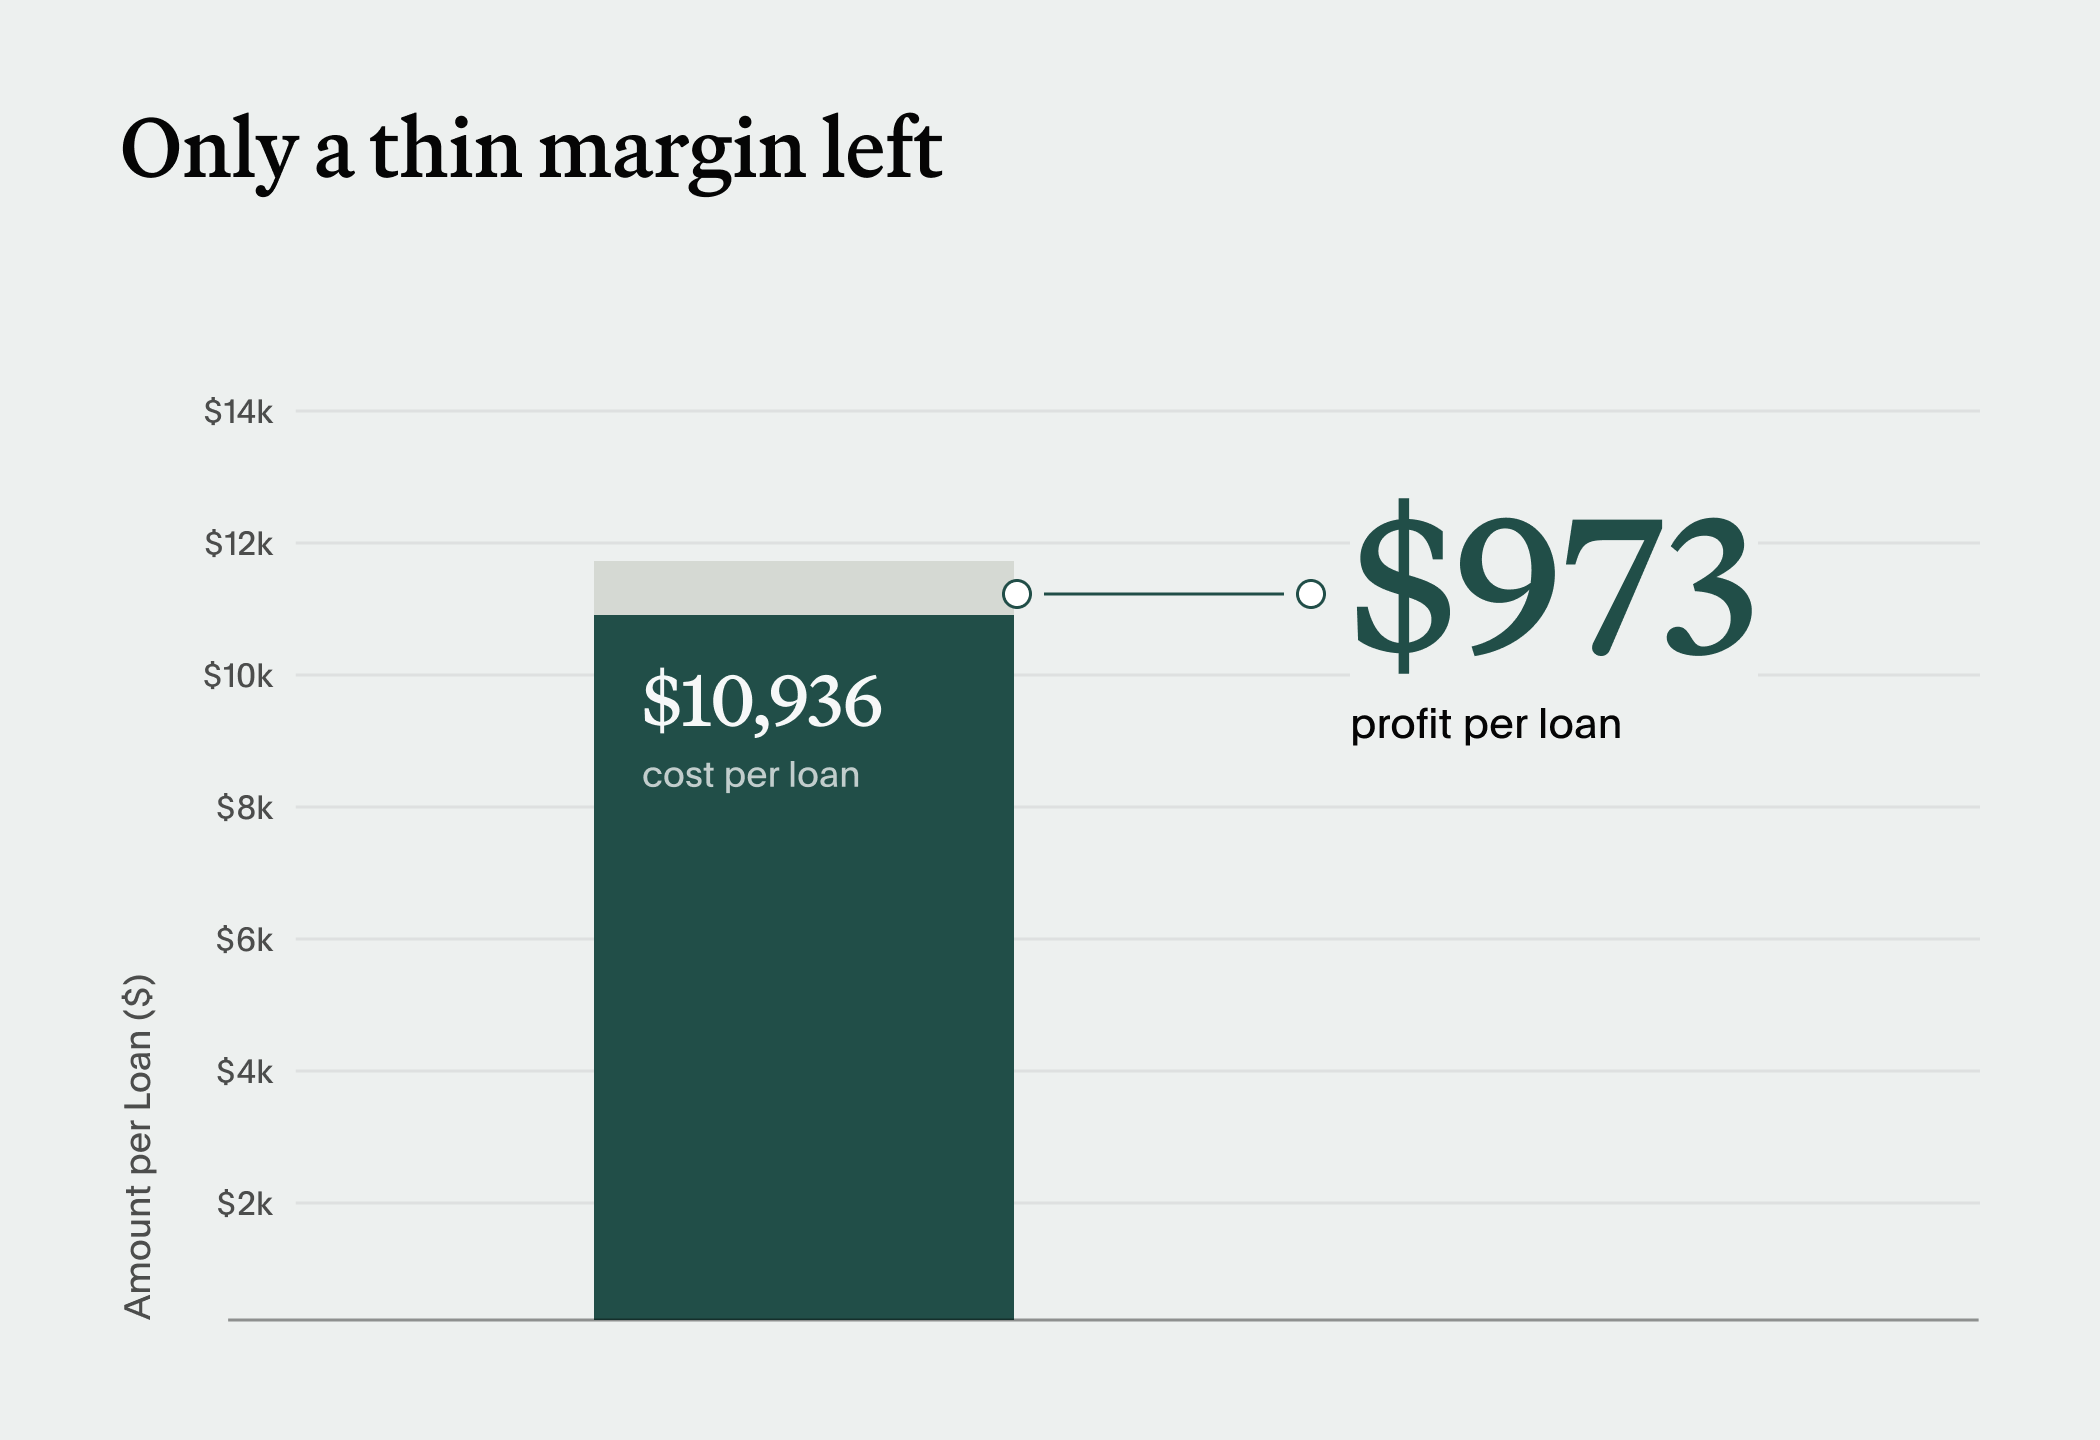
The 2026 market doesn't make this easier
Three structural facts about this year keep the cost pressure on.
This is a purchase market. MBA projects $2.2 trillion in single-family originations for 2026, split roughly $1.46 trillion purchase to $737 billion refinance. Purchase loans made up 80% of first mortgage originations by dollar volume among reporting companies in Q2. Purchase loans are more expensive to produce than refis: longer cycles, more borrower contact, more conditions, more re-verification, and a competitive dynamic where turn times decide whether you win the file at all.
Rates are moving the wrong direction. On September 16, the Federal Reserve raised its benchmark rate by a quarter point, to 3.75%–4.00%, citing inflation that "remains elevated." The Fed doesn't set mortgage rates directly — those track longer-term Treasury yields — but the 30-year fixed has kept climbing. Freddie Mac's survey put it at 7.03% on September 24, above 7% for the first time in well over a year — up from 6.95% a week earlier and 6.30% a year ago, and above the 6.0–6.5% range MBA had forecast for the year. Higher rates stretch purchase timelines: more shopping, more extended locks, more files that fall out after the work is done. Each of those adds verification touches, and cost, to the loans that do close.
Volume growth is modest. An 8% increase off 2025 doesn't create the scale that absorbs fixed costs. Per-company production volume did climb in Q2 to its highest level since 2022, and that helped — but modest volume growth won't dilute cost per loan on its own, especially with rates rising into the fourth quarter. It still has to be managed down at the line-item level.
Put together: purchase-heavy pipelines, rising rates, modest volume growth, and margins that remain below their historical average even after a good quarter.
Verification is a line item that grew 272%
Most cost-to-originate analysis focuses on personnel, which is the right place to start — it's the largest component. But verification is one of the few line items with a documented, dramatic price history and a real alternative.
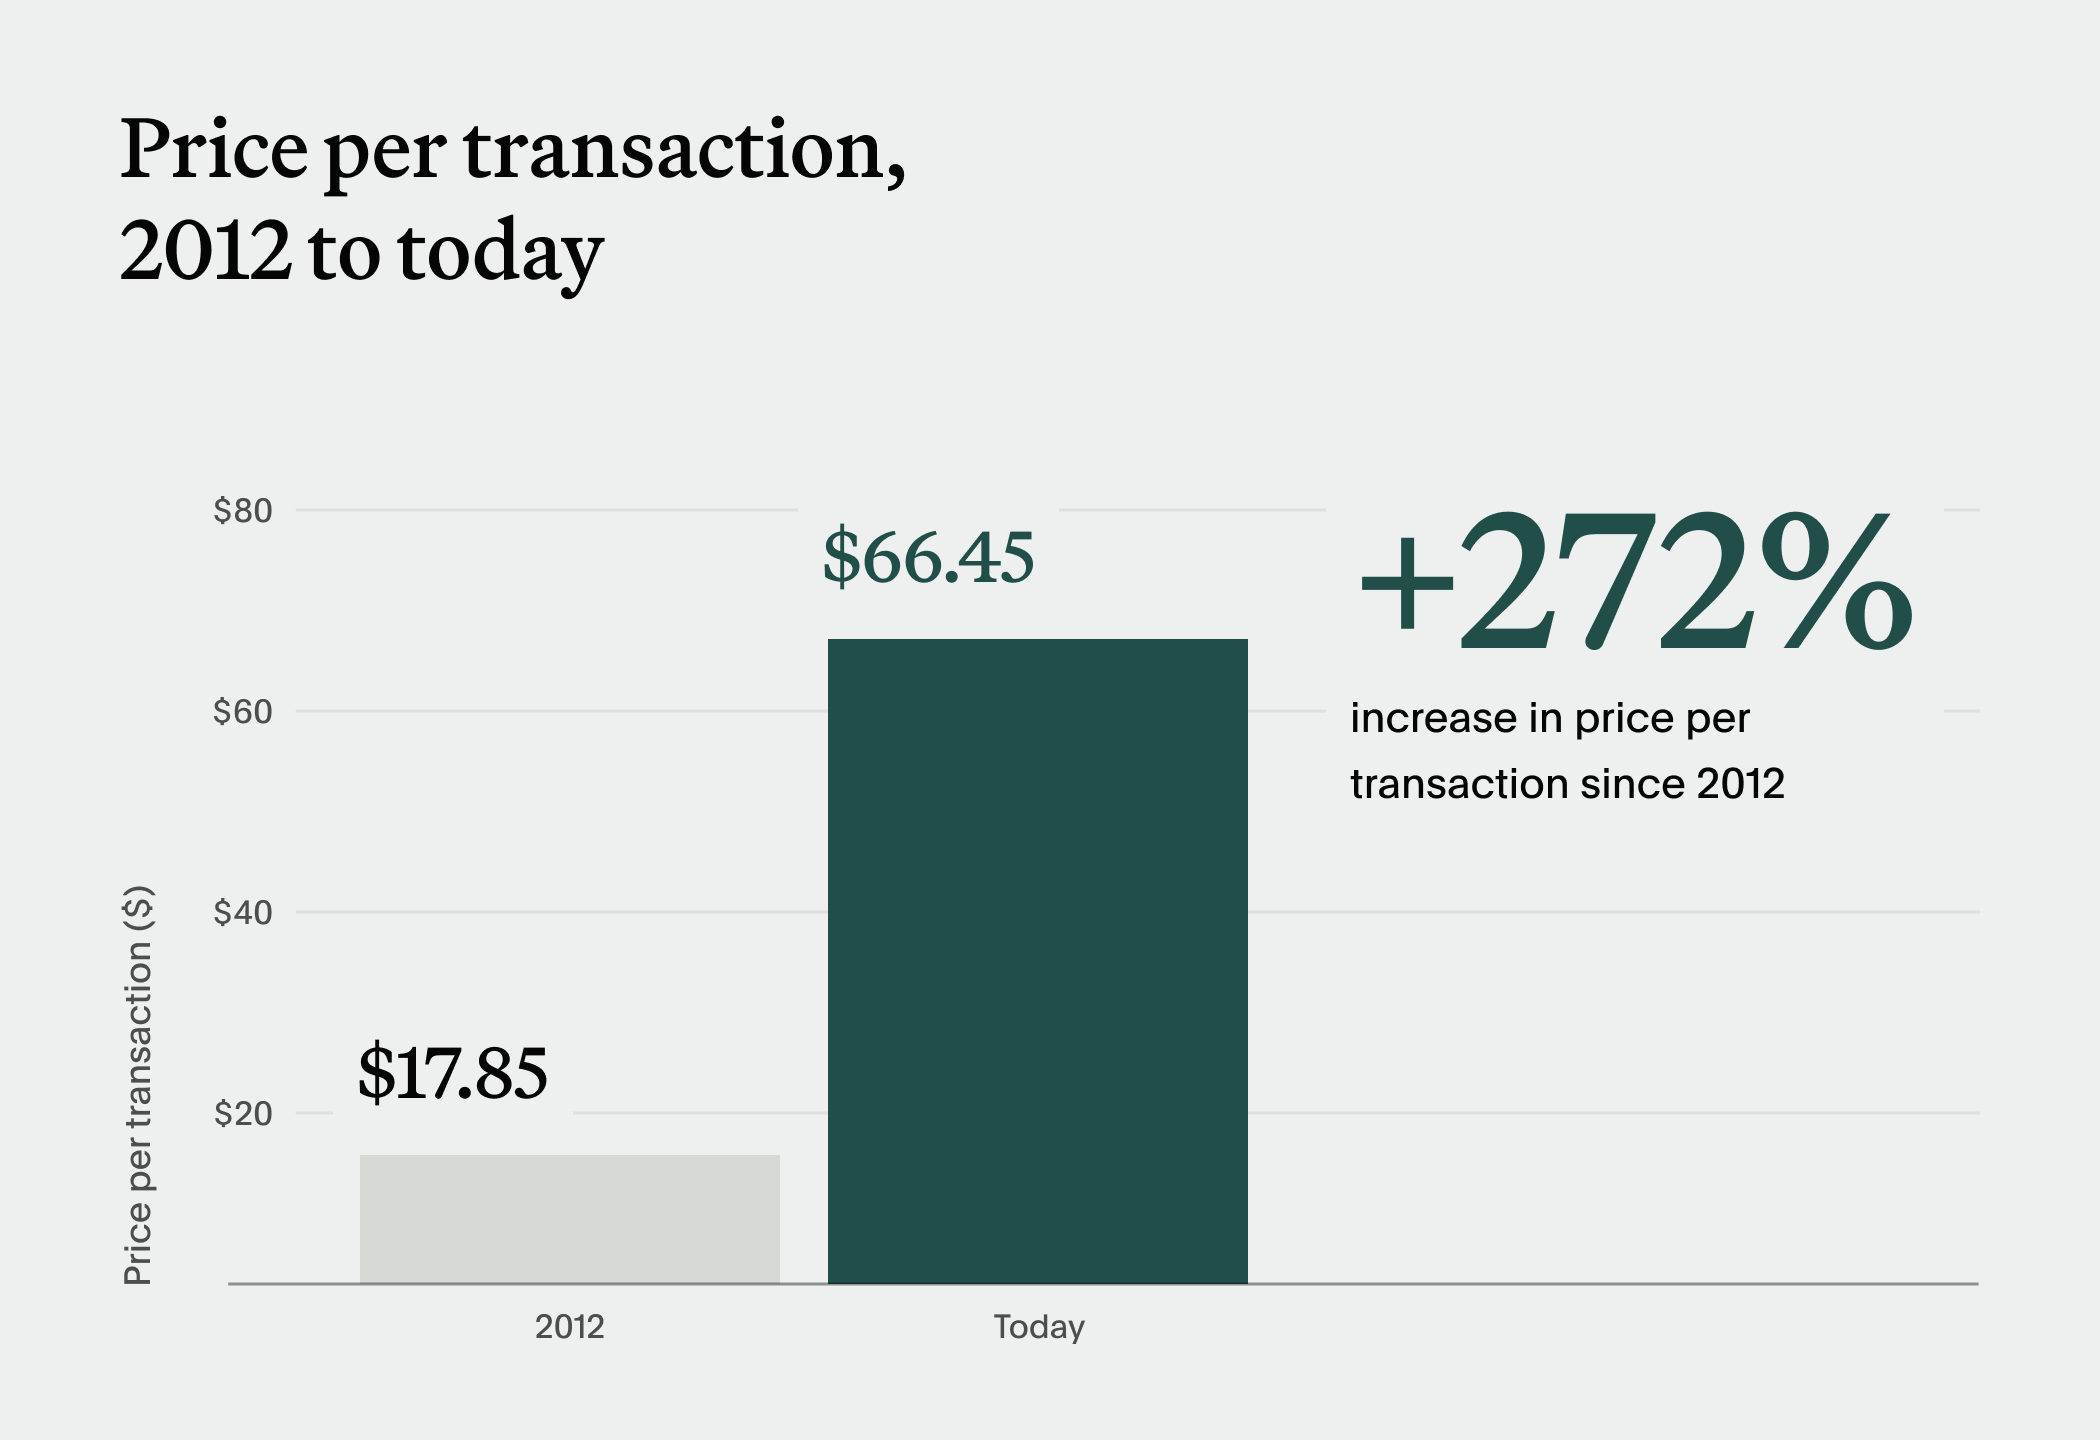
In a class-action antitrust complaint filed in May 2024, lenders First Financial Lending and Greystone Mortgage allege that Equifax's electronic VOIE pricing rose from $17.85 per transaction in 2012 to $66.45 — a 272% increase — with historic records running up to $200 per transaction. The complaint estimates the product generates roughly $2 billion in annual profit at gross margins above 50%, and alleges the pricing is sustained by exclusive payroll agreements and revenue-sharing arrangements that foreclose competitors from a substantial share of necessary data inputs. Equifax has said it will respond to the litigation as appropriate. Separately, the Community Home Lenders of America has publicly urged regulators to examine Work Number pricing.
Those allegations are for a court to resolve. The pricing trajectory, though, is the thing lenders have to plan around regardless of how the case comes out.
The math lenders usually skip: pulls per loan, not price per pull
Here's where verification costs quietly exceed the budget line.
Most lenders don't pull VOIE once. A typical purchase file involves an initial verification at application, and a re-verification of employment close to closing — GSE requirements make that second touch standard, not optional. Files with conditions, income changes, co-borrowers, or multiple employers add more. Extended rate locks in a slower, higher-rate purchase market add more still.
So the real unit is not the price of a pull. It's price per pull × pulls per file × files in your pipeline.
At $66.45 a pull and two pulls on a clean file, verification runs roughly $133 per loan — about 14% of the $973 average per-loan production profit in Q2. Add a third pull on a file with a condition and it's about a fifth of the margin. And margins move: against Q1's $727 profit, the same two pulls would have consumed about 18%. Across 5,000 units a year, the difference between a two-pull file at $66.45 and one at a fraction of that price can easily run into six figures.
This is also why per-pull pricing and per-loan pricing aren't interchangeable, even at similar headline rates. Per-pull pricing puts the cost of a messy file on you. It also creates a quiet incentive to under-verify — to skip a re-pull you should have run — which is exactly the wrong pressure to introduce into a loan quality process at a moment when income misrepresentation accounts for a large share of detected mortgage fraud and GSE privatization is sharpening rep-and-warrant scrutiny.
Where the cost actually comes out
Three levers, in order of impact.
Put the highest-yield source first in the waterfall. The most expensive verification is the one that fails and falls through to a slower, costlier path — or to a human. When applicants connect their own payroll accounts and share records straight from the source, the file resolves in seconds, and the expensive fallbacks only get used on the files that genuinely need them. Argyle's consumer-permissioned verification platform — where applicants direct the sharing of their own records — covers 91% of the U.S. workforce for payroll income and 95% of direct deposit accounts.
Count conversion honestly, because failed attempts are pure cost. A verification attempt that an applicant abandons costs you the cycle time, and often a manual touch — and in a purchase market it can cost you the borrower. Measure net conversion across everyone who starts the flow, not just those who finish it. Argyle has seen an average of 72% for customers combining direct-source payroll and document-based verification flows.
Price the cycle time, not just the fee. In a purchase market, days are a competitive weapon. Lake Michigan Credit Union reported cutting up to three weeks from verification time and saving up to $100 per loan after moving to consumer-directed verification; NFM Lending reported up to 80% savings versus legacy providers in its first year. First Financial Bank reported up to 60% verification cost savings. Lenders using Argyle report closing loans 12+ days faster.
How to run the numbers on your own pipeline
A defensible internal estimate takes four inputs:
- Your actual verification pulls needed per funded loan, from the last two quarters — not the assumed number. Most lenders find this is higher than they expected.
- Your cost per pull, including historic-record surcharges and re-verification fees.
- Your fallout rate on verification attempts, and the cost of the manual work those failures generate.
- Your cycle time attributable to verification, in days, and what a day is worth in your purchase pull-through.
Multiply the first two, add the third, and weigh the fourth against your competitive position. That number is your real verification cost. It is usually well above the line item in the budget, because the line item only captures the fee.
The bottom line
At $10,936 to originate and $973 to keep — with rates heading higher into year-end — there is no line item too small to examine, and verification is not a small one. It's a cost that has risen sharply, that multiplies by a factor most lenders don't track, and that has a direct alternative: records the applicant shares straight from the source, priced for a market that can't absorb 272% increases.
If you'd like help modeling verification costs against your own pipeline, reach out to our team.