About RWM Home Loans
Headquartered in San Diego, California, RWM Home Loans is an independent mortgage bank operating in the retail channel. Over the past three years, RWM has been one of the fastest-growing mortgage companies in the country. From 2023 to 2025, RWM grew from 81 to 154 producing loan officers, a 90% increase in retail loan officers focused on purchase production, while annual funded volume climbed from $306 million to more than $1 billion, a 227% increase. That growth has carried into 2026, with RWM on track to serve more than 3,000 borrowers this year. The expansion happened organically, without mergers or acquisitions, and RWM's licensed footprint grew from about 21 states in 2024 to more than 30 states today, all while holding onto the culture and service standards that fueled the growth in the first place.
Challenge
For about four years, RWM worked with a different verification solutions provider, relying on asset verification supplemented by an income data feed.
As the relationship with its provider evolved, RWM found the level of service wasn't keeping pace with what the business needed.
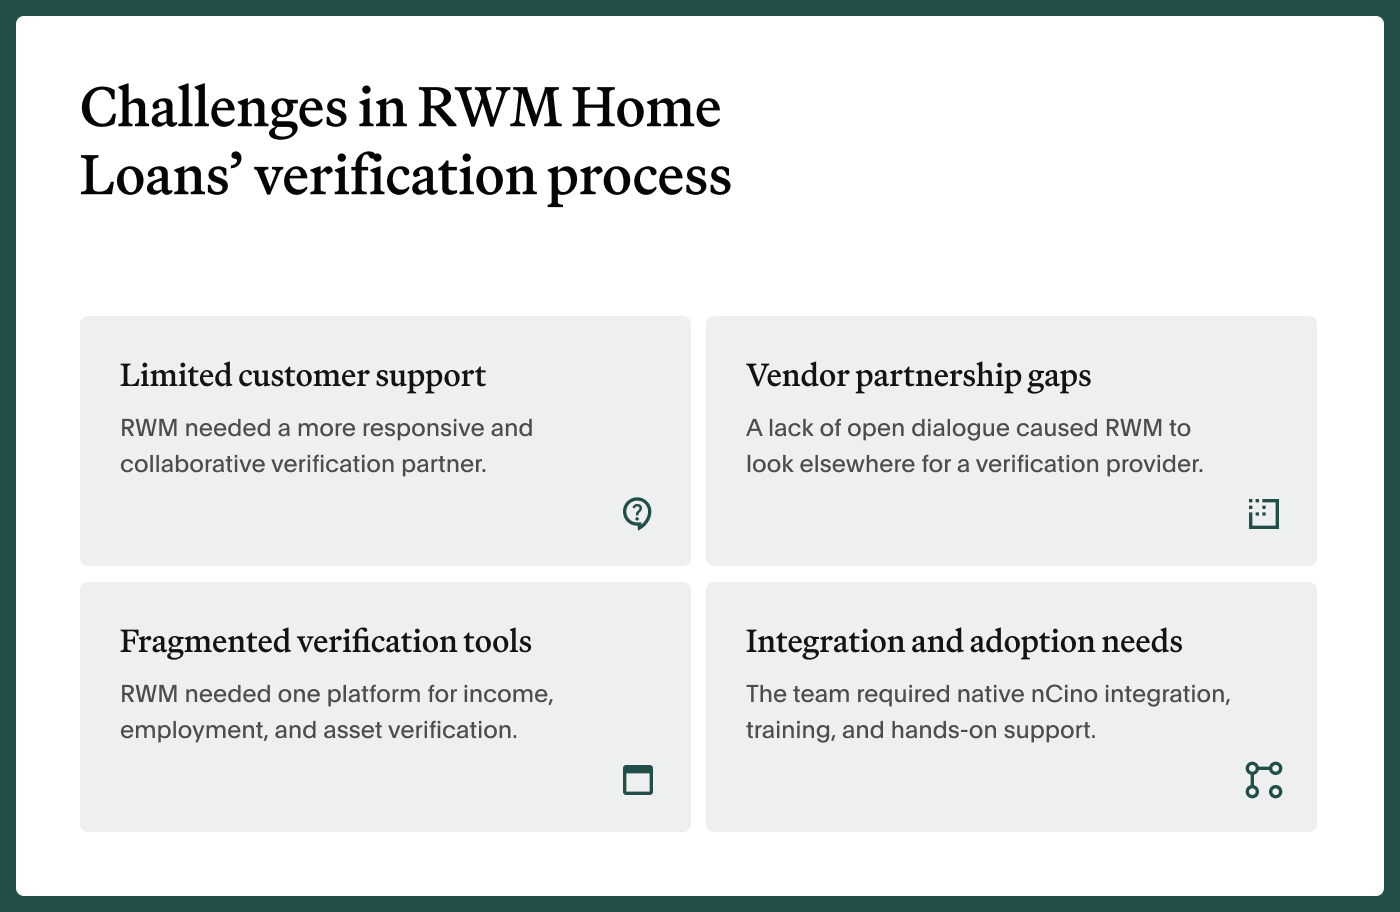
"We weren't getting great customer service, and it wasn't achieving certain goals of ours," said Greg Pettersen, EVP of Growth & Innovation at RWM Home Loans. "We like to pick quality vendors we can have an open dialogue with and build a strong partnership with. Anytime that's lacking, we look at what else is out there."
RWM had a specific set of requirements for its next verification partner: one platform covering income, employment, and asset verification, a native integration with its point-of-sale (POS) system nCino, and a team willing to invest in training and adoption rather than just software.
Solution
As time went on, that vendor started building its own payroll verification tool and ultimately incorporated Argyle's technology into its platform, which is how RWM first came into contact with Argyle. RWM then assessed Argyle on its own and decided to consolidate income, employment, and asset verification entirely with Argyle. RWM Home Loans came on board as an Argyle customer in October 2025, deploying Argyle across both its nCino POS platform and its loan origination system, Encompass by ICE Mortgage Technology.
Rather than restrict Argyle to a single role or stage in the loan process, RWM made a deliberate choice to put it first in line on its verification waterfall and open it up to anyone touching the loan.
"We're not trying to gatekeep or only allow it to be ordered at a certain point," Pettersen said. "We don't care who orders it, whether it's the borrower, a loan officer assistant, or a loan officer. We want to empower our team to be successful, and that's helped reduce loan fallout, increase borrower conversion, and create a lot of efficiency as files get put together."
That access shows up early in the process. Loan officers frequently step into files where a borrower has already connected asset and payroll data through nCino, giving them a full financial picture of the borrower before the conversation even starts.
RWM credits much of its adoption success to how it has approached Argyle internally, and Pettersen pointed to a few things that made the difference.
Introducing Argyle at the very start of the loan process, rather than later in underwriting, has been key to getting the full benefit. Training and buy-in from the front line matter as much as the technology itself, and RWM has leaned into that by turning its highest adopters into champions who talk directly to peers, and by putting adoption and cost savings numbers in front of branch managers so the impact is visible in real dollars. At the executive level, RWM has removed role-based restrictions so that anyone on a loan team can run Argyle whenever it adds value.
"Your team actively listens, communicates the roadmap, and regularly incorporates customer feedback into future development," Pettersen said. "That level of engagement makes Argyle feel like a true strategic partner rather than another software vendor."
One of RWM's top-producing branches is also its highest Argyle adopter, having all but eliminated The Work Number orders for employment verification through consistent borrower education and full team commitment.
Outcome
- 50% of verification orders now run through Argyle
RWM processes roughly 600 to 700 verification orders a month. Of those, 300 to 350 are Argyle.
"Being first in our waterfall wasn't just a policy decision, it's showing up in the numbers every month," Pettersen said. "Argyle is handling half of our verification volume today, and we still have branches with room to grow into that."
- 35% reduction in verification costs
Placing Argyle at the top of the waterfall and encouraging broad use across the team has driven a steady decline in reliance on The Work Number. RWM tracks this closely at the branch level.
"We are continuing to tell our branch managers to leverage Argyle, and we're seeing reductions in verification costs of up to 50% across many of our branches," Pettersen said. "One of our top adopters had zero The Work Number charges in his most recent monthly branch review. Our high adopters and branch managers who are really buying in, the results are clear, and they're seeing it."
- Meaningful time savings across the file
RWM estimates Argyle saves roughly 30 minutes for the borrower, 45 minutes for the LO or LOA, and about an hour each for processing and underwriting, with underwriting time varying based on Rep and Warrant layers on a given file. RWM has also seen more complete loan files and lower loan suspense rates, which the team attributes directly to direct-source data improving accuracy and turnaround.
"When everyone from the borrower to the underwriter is spending less time chasing documentation, that time goes right back into the loan," Pettersen said. "We're seeing more complete files come through the door, and lower suspense rates because of it. That's Argyle's direct-source data doing its job before the file ever gets stuck."
- R&W relief across 10% of conventional loan files
About 10% of RWM's conventional loan files carry multiple layers of Reps and Warrants across assets, employment, and income, giving the team a meaningful pool of loans where Argyle's coverage reduces risk exposure and supports GSE rep and warrant relief.
"Any file carrying multiple layers of Reps and Warrants is a file with reduced risk exposure for us," Pettersen said. "Argyle helps us close that gap on a meaningful share of our conventional volume, and that's risk we're simply not holding anymore."
- Turning ineligible findings into closed loans
One of the more unexpected wins for RWM has come from asset verification. When a conventional loan receives an ineligible finding from Fannie Mae or Freddie Mac through Desktop Underwriter, RWM's team checks whether a VOA report with connected accounts, including direct deposits and rent payments, changes the outcome. The GSEs weigh cash flow and rental payment history heavily, and RWM has seen that data flip ineligible findings to eligible on multiple occasions.
"A loan we couldn't do, we're now able to do, just from that VOA connection," Pettersen said. "The loan officer gets a new loan, the borrower gets the home they wanted, and we get a loan we wouldn't have had otherwise. In an environment where every loan counts, turning a no into a yes is a win for everybody."
Taken together, these habits point to something bigger than one integration. RWM treats Argyle as core infrastructure, not an optional tool a few processors happen to use. That mindset, backed by training, incentives, and executive buy-in, is what turns a good product into a company-wide result.
"Argyle has become a foundational part of how we streamline the mortgage process, improve operational efficiency, and enhance the borrower experience," Pettersen said. "Argyle's ability to help us streamline income, employment, and asset verification, improve data quality, reduce documentation burdens, and accelerate decision-making has supported the scalable platform that lets our loan officers be more productive."